Who released these funds, and on what basis?
Sooner or later, every fiduciary gets asked that question by a court, an auditor, a supervising trustee or a claimant. The answer has to exist before the question is asked.
A settlement usually gets reported when the number is agreed and the order is signed. For the fiduciary, that is where the work starts. Money that belongs to other people has to be held correctly, often for months, and then paid out correctly, on the record, under the eye of parties who can hold you personally liable if it goes wrong.
This post covers the custody and disbursement problems fiduciaries face, where they usually break, and what it takes to prove you did the job.
Why fiduciaries carry a different burden
A payments team moves money. A fiduciary has to hold and move money it doesn't own, for beneficiaries it is obliged to treat fairly, within the limits of a trust or settlement agreement it didn't write. It also has to account for every decision along the way.
In practice, that means a set of duties that ordinary payment operations don't carry:
- The duty to segregate. Settlement funds must never mix with operating money.
- The duty to follow the governing instrument. Every release has to be authorised by the trust, order or agreement.
- The duty of impartiality. No beneficiary is favoured, delayed or shortchanged.
- The duty to account. At the end, you have to show where every dollar went.
Each disbursement problem below is really one of these duties under strain.
Know what you are holding
The vehicle decides your duties: who the fiduciary is, who supervises, how the money is taxed and what the final accounting looks like.
- Qualified Settlement Funds are court-supervised trusts with their own tax identity and a fiduciary administrator. They are the standard vehicle for mass tort and class action settlements, and increasingly for single plaintiff settlements too.
- Attorney trust and IOLTA accounts are held by the law firm under state bar rules. They are the default for smaller settlements and have the least third party oversight.
- Third-party escrow is held by a bank or trust company and released on agreed conditions.
- Court registry and receivership accounts are disbursed only on court order.
- Bankruptcy and claims trusts, such as §524(g) asbestos trusts, pay claimants over years from a fixed corpus.
- Regulatory restitution funds, such as SEC fair funds and CFPB or state AG accounts, distribute to victims under government supervision.
Because the label "settlement fund" gets borrowed, the first job is to confirm what you are actually holding. A genuine settlement account has four features:
- a settlement, judgment or claim it exists to resolve
- a payor who is not the beneficiary
- someone accountable for the funds as a fiduciary
- a clear tax identity
Custody: holding it right
Custody is where fiduciary risk begins, long before a single payment goes out. Three questions matter from the day funds land:
- Who owns the money? Beneficial ownership has to stay with the beneficiaries, and the account structure should show it.
- Is it segregated? Settlement funds must be walled off from operating accounts, with no commingling, even temporarily.
- Where does the interest go? It goes to the client, the fund or the IOLTA program, and never to the holder.
Get the custody structure wrong and every correct disbursement that follows still sits on a non compliant foundation.
Disbursement: six places it breaks
1. Funding. The record of a distribution starts when the money lands. In most operations, someone notices a balance and emails a colleague, and that email becomes the number everything downstream reconciles against. Funding is also the moment to classify each amount as principal, expenses, fees, interest, taxable or excluded. Classified then, the information travels with the money. Classified later, it has to be reconstructed. Duty at risk: accounting.
2. Deductions. Between funding and payment, the gross award is reduced by fees, liens and holdbacks. Each deduction needs a source, a date and an authority traceable to the claimant. An unsupported deduction is money taken from a beneficiary without a basis. Duty at risk: following the governing instrument.
3. Tax. Every holder has to collect tax forms from payees at scale, withhold where they are missing, and separate taxable from excluded amounts for each payee. Errors here are filing failures, and they belong to whoever holds the funds. Duty at risk: accounting.
4. Payees and approval. Payees are rarely simple. Estates, minors, trusts and municipalities each need their own documentation, often court approval, and they carry the most liability. Release usually depends on sign-off between the administrator and the law firm or trust, typically by a signed PDF in an email thread.Duty at risk: following the governing instrument.
5. Execution. Money leaks at the point of payment through stale addresses, returned payments, duplicates, uncashed checks and bank details changed by a convincing email. Every failed payment lowers take-up, grows the unclaimed balance and leaves some beneficiaries unpaid while others are paid.Duty at risk: impartiality.
6. Visibility. A distribution has to stay visible to the court, trustee, administrator, law firms, lien holders and claimants, and they rarely share a system. When status lives in spreadsheets, every enquiry becomes a manual report.Duty at risk: accounting.
The final accounting
All of this comes due at the end. The final accounting has to show that every dollar reached a claimant, an authorised deduction or the residual, and that every step was taken within the fiduciary's authority.
This is the fiduciary's defence. When the distribution ran on email and spreadsheets, that defence has to be assembled after the fact. When each event was captured in a system of record as it happened, the defence already exists.
The account might be a firm's IOLTA holding one client's award, or a QSF paying 50,000 claimants. Either way, the question is whether each event was recorded when it happened. In most operations, careful people are running a fiduciary process on tools built for a general ledger and an inbox.
Where Talli fits
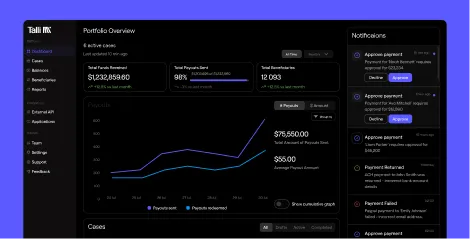
Talli is a disbursement platform built for fiduciaries, trustees, administrators and law firms. Each point above has a matching control:
- Custody. Funds are held in a structure where ownership stays with the beneficiary and money stays segregated from operating funds, so you are compliant from the day it lands.
- Classification. Every transaction can carry tags with whatever metadata the matter needs, such as principal, fees, liens, holdbacks, or taxable versus excluded. The classification made at funding travels with the money to payout.
- Tax. Talli collects W-9s from beneficiaries at the point of payment and provides the 1099 data, ready for you to file.
- Approval. Release runs through a defined workflow between the administrator or fiduciary and the law firm or trust, instead of a signed PDF and an email chain.
- Execution. Beneficiaries are paid by prepaid card, ACH, Venmo, PayPal, gift card or check, whichever suits them, so fewer payments fail, bounce or go uncashed.
- Visibility. Trustees, administrators and law firms can be given access to specific distributions and can check on them at any time.
- Accounting. A real-time distribution ledger records every event as it happens, including funding, deductions, approvals and payouts, so the balance of each distribution is always current and fully traceable. Reporting and attestation draw directly from that ledger to show you operated within the roles and responsibilities set by the trust or settlement agreement. That evidence comes from the record rather than being rebuilt after it.
The result is that more money reaches claimants, less goes unclaimed, and the record holds up under review.